PVC
Industry Status
China's PVC capacity expanded rapidly. By 2013, the domestic capacity hit 26.01 million tons per annum and the output stood at 15.4 million tons. It was projected to exceed 30 million tons per annum in 2015. Due to overcapacity, the average operating rate of the industry lingered between 55% and 60%. With the launch of new production lines and products, China's reliance on imports has gradually declined in recent years, and the domestic self-sufficiency rate has reached 98%.
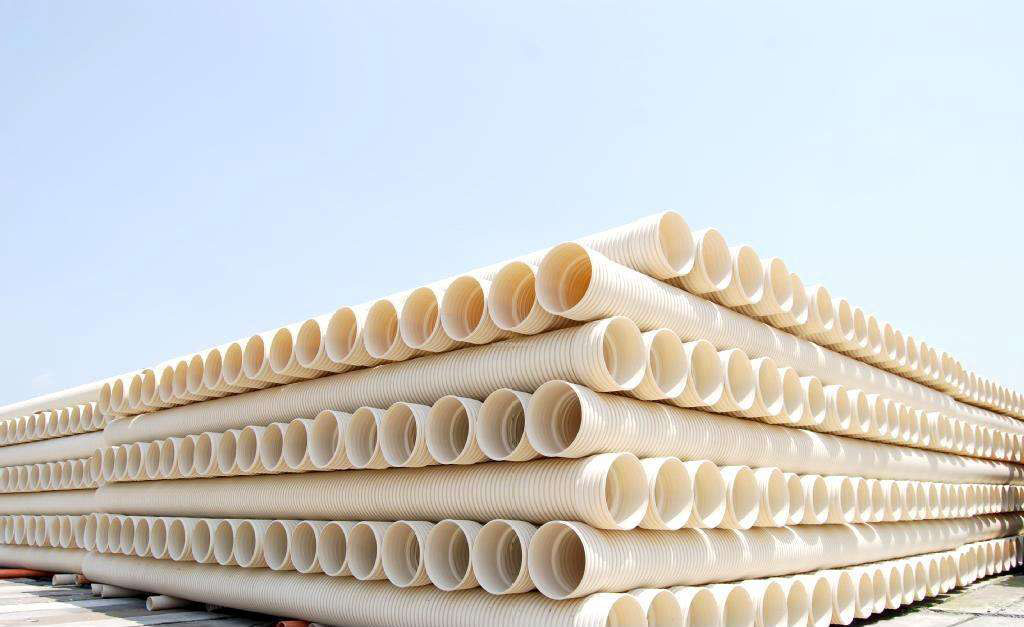
Competition for conventional PVC raw materials used in building profiles, sheets, films, pipes and cable materials has become increasingly fierce. Nevertheless, high-end special-grade materials for medical and food applications still mainly rely on imports. Domestic PVC consumption is primarily concentrated in South China and East China. Provinces including Guangdong, Zhejiang, Fujian, Shandong and Jiangsu contribute 70% of the national total consumption. The South China market, led by Guangdong and Fujian, has huge demand but insufficient local capacity, resulting in a large share of supply from imports and inter-regional transfers. The East China market, centered on Jiangsu and Zhejiang, hosts numerous manufacturers yet still cannot fully meet local demand, with import and transferred volumes second only to South China.
Industry Trends
A number of large-scale PVC production facilities will be newly built or put into operation in China in the coming years, while backward small-capacity units will be phased out. It is estimated that in 2015, China's total PVC capacity would reach 27.1 million tons per annum with a demand of 16.6 million tons. Net imports would drop to around 150,000 tons and the operating rate would stand at 62.0%. By 2020, the capacity would rise to 28.3 million tons per annum and the output to 19.6 million tons. China would turn into a net exporter with the operating rate climbing to 72.8%, though overcapacity would still persist.
Over the past two years, international crude oil prices have stayed at around 100 US dollars per barrel, pushing up the cost of ethylene-based PVC, while falling coal prices have given calcium carbide-based PVC a distinct cost advantage as it is less affected by oil price fluctuations; central and western regions such as Xinjiang, Inner Mongolia, Shanxi, Ningxia and Sichuan have capitalized on local resource advantages to build and expand PVC facilities, resulting in a sharp rise in domestic production capacity. In the future, calcium carbide-based PVC enterprises will face great pressure from environmental regulations and severe overcapacity, and those with backward production capacity and no upstream resources will be phased out, driving the industry to develop toward integration and large-scale operations. Most imported PVC products are special-purpose materials or products with excellent performance and modification properties, which domestic products cannot match, yet their prices are relatively high due to import tariffs and anti-dumping duties, so they are mainly applied in processing with supplied materials and re-export trade rather than domestic demand.
Summary
The share of calcium carbide-based PVC will further increase and dominate the entire industry. Meanwhile, ethylene-based PVC producers will have to pursue continuous innovation, covering high-end application development, process upgrading, niche market expansion and flexible production line transformation, so as to build their own high-end market segments.